Minda Corporation Ltd. – Systems in Motion
Minda Corporation Limited, the flagship company of the Spark Minda Group, is a leading Indian automotive component manufacturer incorporated in 1985 and headquartered in Noida. The company operates as a multi-product, multi-vertical Tier-1 supplier, catering to two-wheelers, three-wheelers, passenger vehicles, commercial vehicles, off-road vehicles and the aftermarket. It has an established presence across India, with international operations spanning ASEAN, Japan and Europe. As of FY26, the company operates 42 manufacturing plants, supported by a workforce of over 23,000 employees, two technology centres, seven engineering centres and an in-house engineering team of over 1,000 professionals. Its focus on technology and innovation is reflected in its portfolio of 330+ patents filed, of which 147 had been granted as of March 2026. Its manufacturing facilities are primarily located across key Indian automotive hubs, including Pune, Pantnagar, Gurugram, Noida, Bawal and Chennai, alongside overseas operations in Indonesia and Vietnam.
Products and Services
The company functions across 6 core business platforms:
- Electrical Distribution Systems: Wiring harnesses, connectors, power distribution units (PDU), battery distribution units (BDU), high-voltage EV wiring harnesses, smart junction boxes and EV high-voltage connection systems.
- Information and Connected Systems: Digital cockpits, shark-fin antennas, telematics modules, smart electronic boards, wireless chargers, motor controllers and cameras.
- Vehicle Access Systems: Smart passive entry and passive start (PEPS) systems, digital keys, electronic steering column locks, flush door handles, access control modules and advanced switches.
- EV Systems and Power Electronics: Electric motors, traction motors, motor controllers, vehicle control units, battery management systems, charging interfaces, on-board chargers, electric drivetrains and other power electronic components.
- Lightweighting and Plastic Components: Centre consoles, cylinder head covers, engine mounting brackets, battery trays, sunroofs, sunshade assemblies, EV motor housings and fuel pumps.
- Powertrain Systems: The company is expanding its presence in powertrain solutions through newly established joint ventures and strategic partnerships, with a focus on electric vehicle powertrain.
Subsidiaries: As of FY26, the company has 9 subsidiaries, 3 associate companies and 3 joint ventures.
Investment Rationale
- EV: Powertrain Electronics Build-Out Lifting Content per Vehicle – Minda is building its EV exposure across motors, controllers and high-voltage components, which is expected to raise content per vehicle and deepen its relevance with OEMs. EV accounts for about 10% of Minda’s own revenue (up 40% YoY) and about 14% at group level including Flash. New lifetime orders in Q1 FY27 totalled ₹2,500 crore, with EV above 15%. The 49% stake in Flash Electronics anchors this vertical: Flash supplies traction and EV motors, motor controllers, vehicle control units and high-voltage solutions, and the e2W kit value could rise from ₹12,000–15,000 to ₹35,000–45,000. In Q1 FY27, Flash grew revenue 42% at a 15.4% EBITDA margin (6.6% PAT margin), above Minda’s group margin of about 11.5%. EV is now about 30% of Flash’s revenue and growing about 90% YoY. The Turntide JV, signed in March 2026 with Minda at 49%, covers motor controllers, axial flux motors and thermal pumps. Sanco localises high-voltage connectors and cell contact systems for battery packs.
- New Products and JVs: SOP-Led Revenue Visibility Beyond the Core Business – Minda is adding new product lines through JVs, with orders secured before production begins. The Toyodenso JV (Minda 60%) takes the company into advanced switches: lifetime orders exceed ₹1,000 crore, the Noida plant is under development, SOP is in Q1FY28 and management expects about ₹150 crore of revenue in FY28. The HCMF JV localises sunroof and closure systems at a Pune facility, with a ₹350 crore lifetime order and SOP this year. Turntide has already won orders in motor controllers, with SOPs from October–November 2026 and facilities in place. At Minda VAST, now consolidated, Q1FY27 revenue grew 22% and the margin rose to 8.4% from 6.5%, supported by flush and bracket-less door handles and electric steering column locks at kit values of ₹8,000–13,000. ECMS approval for display modules, with a planned greenfield TFT line, adds backward integration. The lifetime order book exceeds ₹10,000 crore (about 20% exports), with about ₹2,500 crore added in Q1 FY27. With capacity utilisation at 77–80% and FY27 capex of ₹400 crore, the FY30 target of ₹17,500 crore is about 2.8x FY26 revenue.
- Q1FY27 – Minda reported revenue of ₹1,846 crore in Q1 FY27, up 33.2% YoY and 8.4% QoQ. Consolidating Minda VAST contributed about ₹125 crore, so growth excluding Vast is about 24%. EBITDA rose 35.4% to ₹212 crore, with the margin at 11.46% against 11.28% a year earlier. Reported PAT of ₹206 crore (₹65 crore a year ago) includes a ₹106 crore exceptional gain, net of tax, from the VAST consolidation. Excluding that gain, PAT is about ₹100 crore, roughly 53% higher YoY.
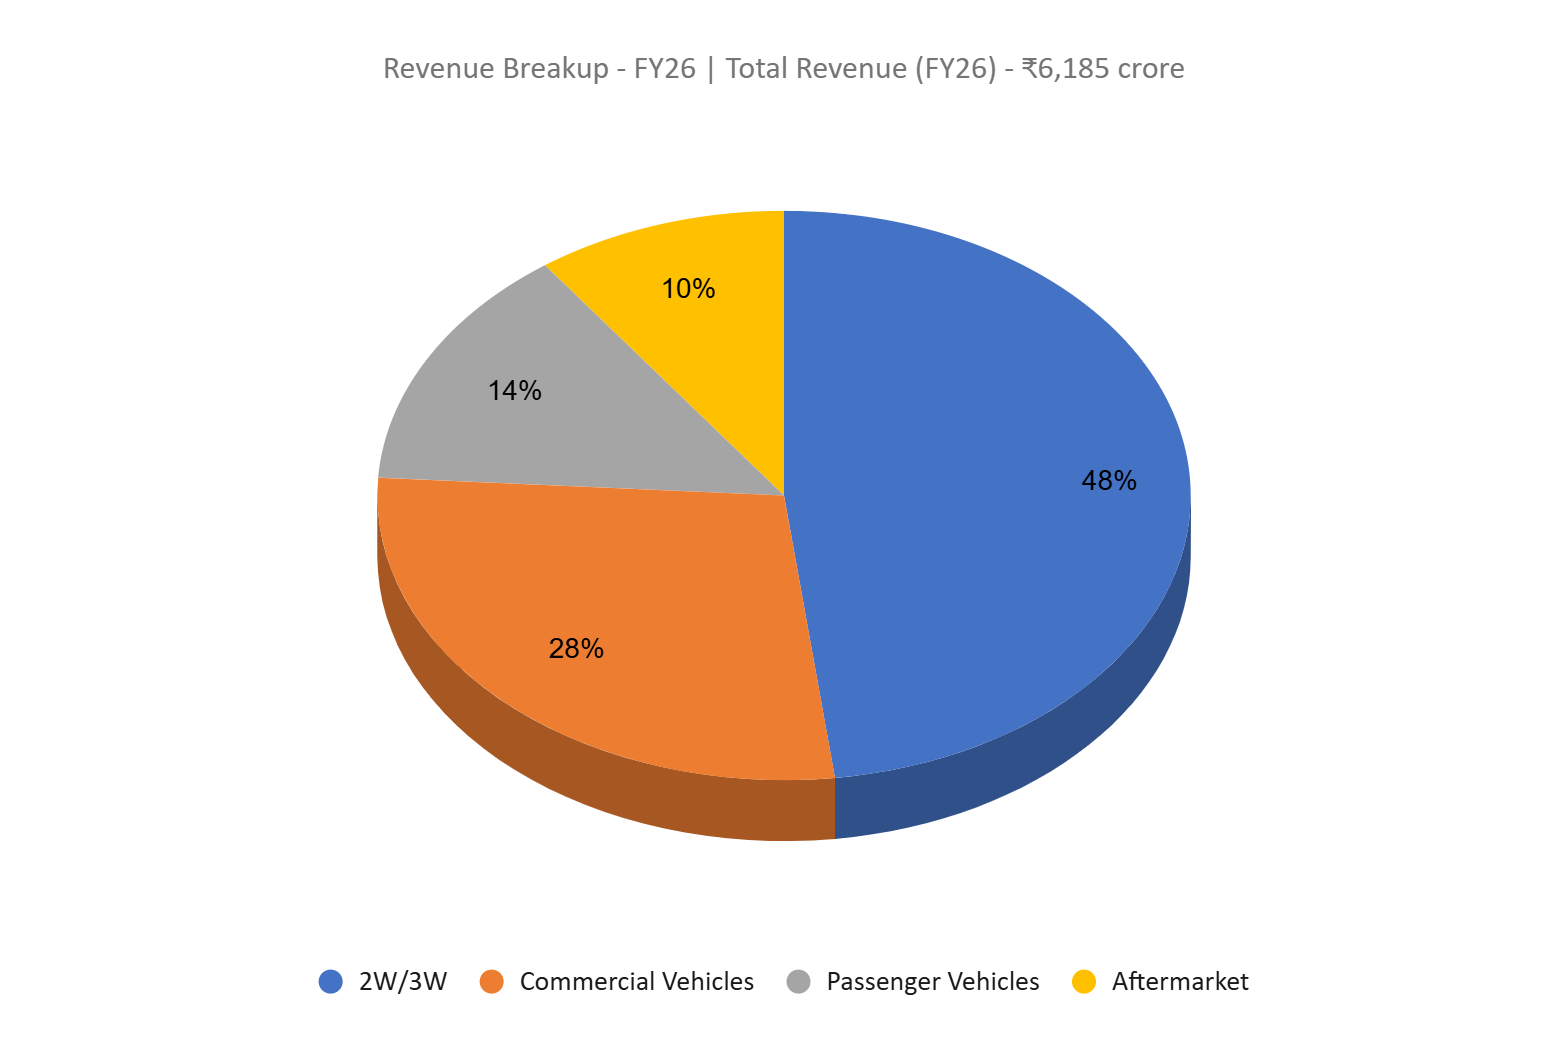
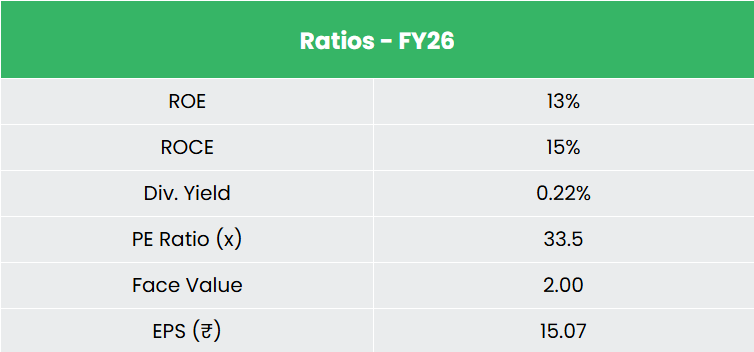
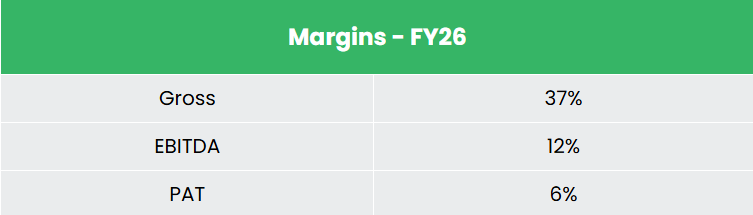
- FY26 – In FY26, revenue from operations (excluding JVs and associates) rose 22.3% to ₹6,185 crore. EBITDA grew 25.5% to ₹721 crore, and the EBITDA margin improved 29 bps to 11.7%. PAT rose 40.3% to ₹358 crore, with the net profit margin up 74 bps to 5.8%. ROCE, excluding Flash, improved from 20% to 23% YoY.
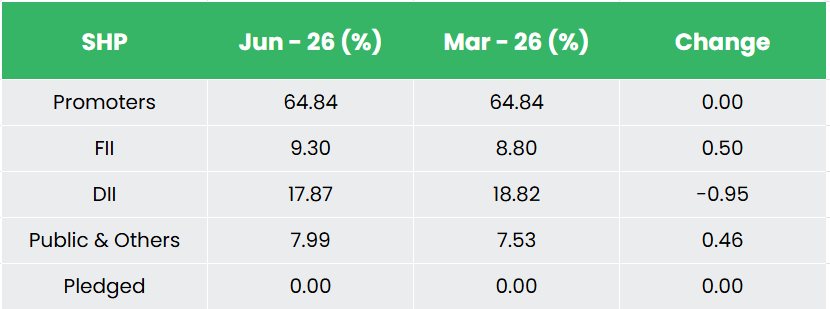
- Financial Performance – The company has generated a revenue and PAT CAGR of 13% and 8% over the period of 3 years while TTM revenue and net profit has grown by 27% and 57%. Average 3-year ROCE is around 21% for FY24-26 period. The company has strong balance sheet with a robust debt-to-equity ratio of 0.56.
Industry
The Indian auto component industry is expected to witness steady growth, driven by rising vehicle demand, increasing EV adoption and localisation of advanced components. India’s EV sales increased by 29.8% to 2.66 million units in FY26, up from 2.05 million units in FY25, with annual sales projected to reach 10 million units by 2030. The EV market is expected to reach US$206 billion by 2030, creating opportunities for manufacturers of electric motors, power electronics and high-voltage wiring systems. Domestic demand remains strong, supported by rising incomes, infrastructure development and two-wheeler sales of 22.2 million units in FY26. Additionally, planned investments of ₹58,000 crore by FY28 to boost localisation of advanced components are expected to strengthen domestic manufacturing capabilities. With exports accounting for over 25% of production, India is also emerging as a key global sourcing hub, supported by its established manufacturing base and access to major automotive markets. Overall, the Indian auto component industry is projected to reach US$111 billion by FY28, supported by domestic demand, EV penetration and export opportunities.
Growth Drivers
- Manufacturing incentives (PLI): The PLI scheme for automobiles and auto components has an outlay of ₹25,938 crore (about US$3.03 billion) for FY23–FY27. It rewards domestic production of advanced automotive technologies, battery and components manufacturing, and supports localisation by suppliers such as Minda.
- Open investment rules: 100% FDI is allowed under the automatic route in auto components, which makes it easier to bring in foreign technology partners and capital.
- EV demand support (PM E-DRIVE and lower GST): PM E-DRIVE, with an outlay of ₹10,900 crore, subsidises electric two-wheelers, three-wheelers, buses and trucks, and funds public charging. ₹2,000 crore is allocated to about 72,300 fast chargers.
Peer Analysis
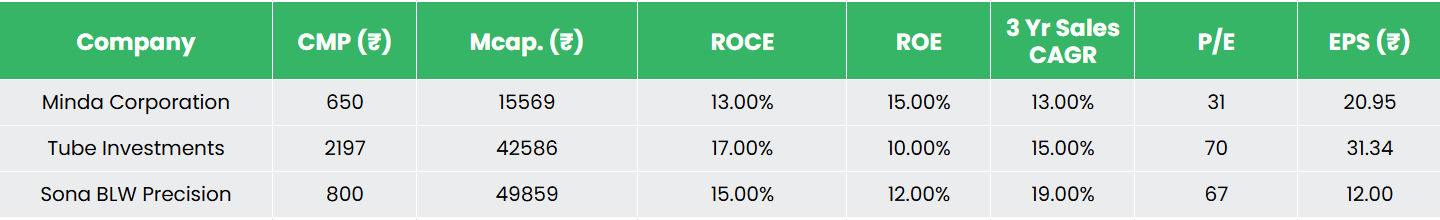
Competitors: Tube Investments of India Ltd, Sona BLW Precision Forgings Ltd etc.
Minda Corporation trades at a relatively attractive valuation compared with Tube Investments and Sona BLW Precision. The company delivers a higher ROE of 15% than both peers, indicating better returns on shareholders’ capital. While its 3-year sales CAGR of 13% is lower than that of its peers, the lower valuation offers a relatively attractive entry point, subject to sustained earnings growth
Outlook
Minda’s FY30 vision targets revenue of ₹17,500 crore (about 3.5x the FY25 base and 2.8x FY26) at an EBITDA margin above 12.5%, against 11.7% in FY26, with export revenue rising to ₹1,500 crore. The company is moving from component supply to integrated system solutions, which raises content per vehicle. In vehicle access, it targets doubling passenger-vehicle kit value by FY2027–28 through smart PEPS, digital keys, electronic steering column locks, flush handles, power lift gates and advanced switches. New platforms include sunroofs (HCMF JV), switches (Toyodenso JV), power tailgates, cockpit domain controllers (Qualcomm collaboration) and EV motors and controllers. Flash is guided to grow 20–24% in FY27, and FY27 capex is guided at ₹400 crore to fund the build-out.
Valuations
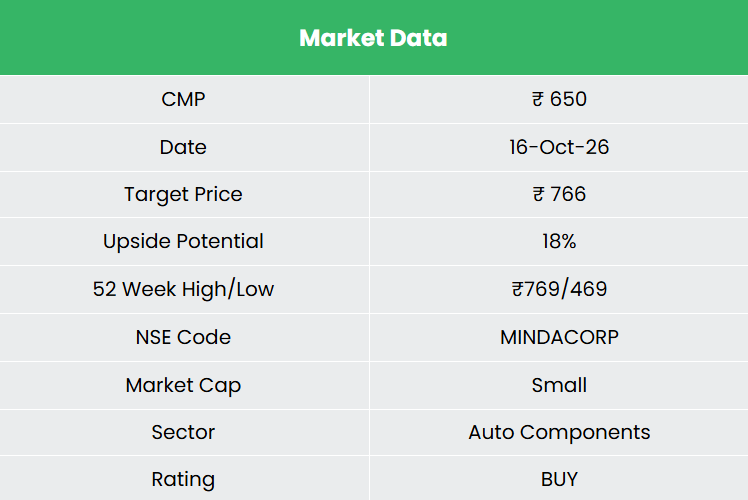
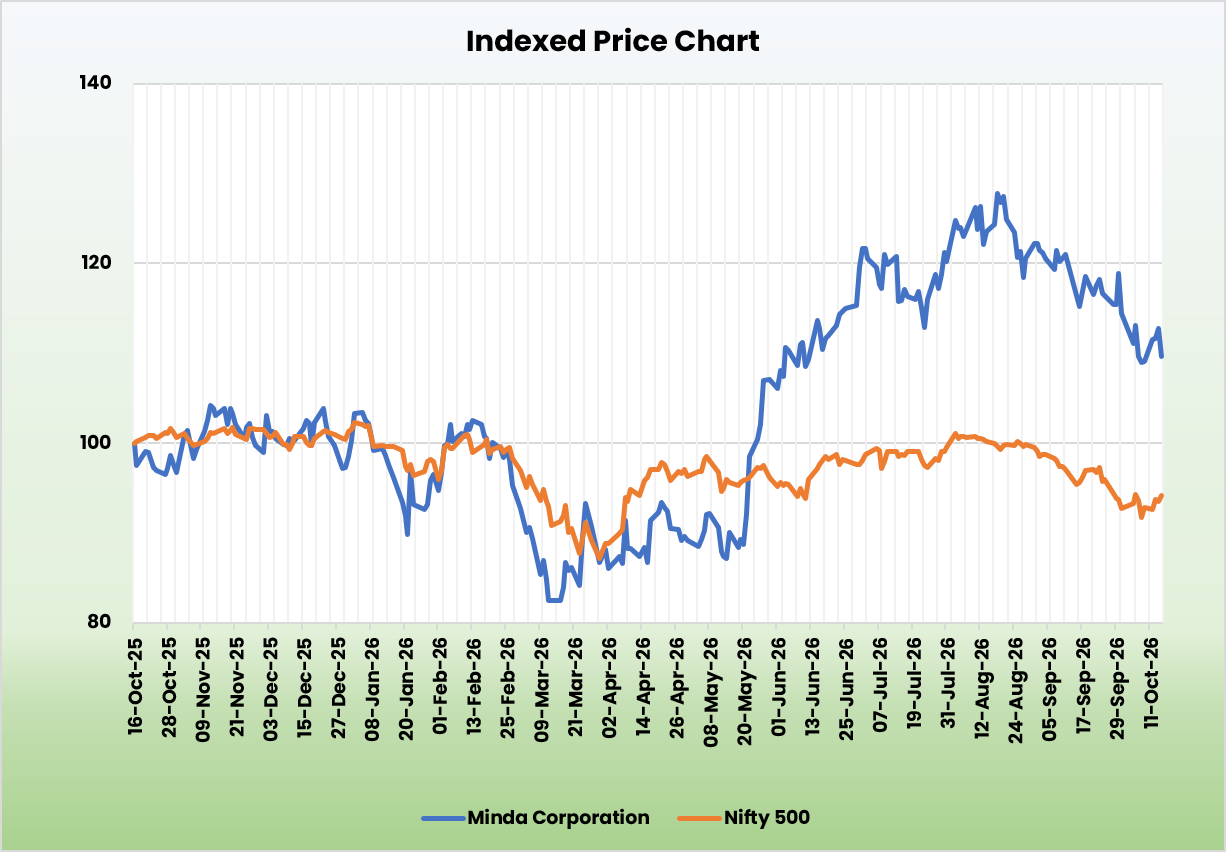
We believe Minda can accelerate its earnings growth through FY30, as the shift to higher-content systems, new JV products entering production from FY27–28, a rising EV mix and margin expansion beyond 12.5% support its ₹17,500 crore revenue target. We recommend a BUY rating in the stock with the target price (TP) of Rs.766, 39x FY28E EPS. We also encourage maintaining a stop-loss at 20% from the entry price to manage potential downside risk effectively.
SWOT Analysis
| Strength | Weakness |
|
|
| Opportunities | Threats |
|
|
Disclaimer: Investments in the securities market are subject to market risks, read all related documents carefully before investing. Securities quoted here are exemplary, not recommendatory. Please consult your financial advisor before investing. Please note that we do not guarantee any assured returns for the securities quoted here.
Research disclaimer: Investment in the securities market is subject to market risks. Read all the related documents carefully before investing. Registration granted by SEBI, and certification from NISM in no way guarantee the performance of the intermediary or provide any assurance of returns to investors.
For more details, please read the disclaimer.